Private credit's growth in the US
Private credit's growth in the US has been closely tied to private equity buyouts, where sponsors often backed asset-light, high-growth technology companies. Over time, this has created meaningful sector concentration in software and tech across many private credit portfolios, where exposure to the software sector is estimated to be approximately 20-35%.
A recent The Wall Street Journal article also flagged that some of the largest US private credit funds may carry 𝗴𝗿𝗲𝗮𝘁𝗲𝗿 𝘀𝗼𝗳𝘁𝘄𝗮𝗿𝗲 𝗲𝘅𝗽𝗼𝘀𝘂𝗿𝗲 𝘁𝗵𝗮𝗻 𝘁𝗵𝗲𝗶𝗿 𝗿𝗲𝗽𝗼𝗿𝘁𝗶𝗻𝗴 𝘀𝘂𝗴𝗴𝗲𝘀𝘁𝘀.
For many years, software was viewed as the “gold standard” for credit underwriting. Recurring revenue, high margins, low capital intensity and strong growth made the sector highly attractive to lenders. 𝙎𝙤 𝙬𝙝𝙮 𝙩𝙝𝙚 𝙘𝙖𝙪𝙩𝙞𝙤𝙣 𝙩𝙤𝙙𝙖𝙮?
Between 2020 and 2022, the leveraged buyout boom in software was heavily financed by direct lending funds. In the race for deal flow, lenders competed aggressively to fund software buyouts, often underwriting at peak valuations and with structures that included PIK toggles. Today, with a maturity wall approaching, refinancing risk is rising. At the same time, generative AI is creating structural disruption across software business models, competitive moats and product cycles.
When presented with opportunities in the tech sector, there are additional factors that one should consider:
1. 𝗧𝗲𝗰𝗵𝗻𝗼𝗹𝗼𝗴𝘆 𝗮𝘀𝘀𝗲𝘁𝘀 𝗮𝗿𝗲 𝗼𝗳𝘁𝗲𝗻 𝗱𝗶𝗳𝗳𝗶𝗰𝘂𝗹𝘁 𝘁𝗼 𝘃𝗮𝗹𝘂𝗲 𝗮𝗻𝗱 𝗿𝗲𝗮𝗹𝗶𝘀𝗲 𝗶𝗻 𝗮 𝗱𝗼𝘄𝗻𝘀𝗶𝗱𝗲 𝘀𝗰𝗲𝗻𝗮𝗿𝗶𝗼. Software businesses are largely built on intangibles: code, customer contracts, brand and talent. 𝘜𝘯𝘭𝘪𝘬𝘦 𝘣𝘶𝘴𝘪𝘯𝘦𝘴𝘴𝘦𝘴 𝘸𝘪𝘵𝘩 𝘵𝘢𝘯𝘨𝘪𝘣𝘭𝘦 𝘢𝘴𝘴𝘦𝘵𝘴 𝘴𝘶𝘤𝘩 𝘢𝘴 𝘳𝘦𝘢𝘭 𝘦𝘴𝘵𝘢𝘵𝘦, 𝘦𝘲𝘶𝘪𝘱𝘮𝘦𝘯𝘵 𝘰𝘳 𝘪𝘯𝘷𝘦𝘯𝘵𝘰𝘳𝘺, 𝘵𝘩𝘦𝘳𝘦 𝘮𝘢𝘺 𝘣𝘦 𝘭𝘪𝘵𝘵𝘭𝘦 𝘧𝘰𝘳 𝘢 𝘭𝘦𝘯𝘥𝘦𝘳 𝘵𝘰 𝘴𝘵𝘦𝘱 𝘪𝘯 𝘢𝘯𝘥 𝘳𝘦𝘤𝘰𝘷𝘦𝘳.
2. 𝗔𝗜 𝗶𝘀 𝗻𝗼𝘁 𝗼𝗻𝗹𝘆 𝗱𝗶𝘀𝗿𝘂𝗽𝘁𝗶𝗻𝗴 𝗯𝘂𝘀𝗶𝗻𝗲𝘀𝘀 𝗺𝗼𝗱𝗲𝗹𝘀 𝗮𝗰𝗿𝗼𝘀𝘀 𝘀𝗲𝗰𝘁𝗼𝗿𝘀, 𝗶𝘁 𝗶𝘀 𝗶𝘁𝘀𝗲𝗹𝗳 𝗰𝗼𝗻𝘀𝘁𝗮𝗻𝘁𝗹𝘆 𝗲𝘃𝗼𝗹𝘃𝗶𝗻𝗴. 𝘈 𝘭𝘦𝘯𝘥𝘦𝘳 𝘱𝘳𝘪𝘤𝘪𝘯𝘨 𝘳𝘪𝘴𝘬 𝘰𝘯 𝘵𝘳𝘢𝘪𝘭𝘪𝘯𝘨 𝘌𝘉𝘐𝘛𝘋𝘈 𝘰𝘳 𝘈𝘙𝘙 𝘮𝘢𝘺 𝘣𝘦 𝘶𝘯𝘥𝘦𝘳𝘸𝘳𝘪𝘵𝘪𝘯𝘨 𝘢 𝘳𝘦𝘢𝘭𝘪𝘵𝘺 𝘵𝘩𝘢𝘵 𝘯𝘰 𝘭𝘰𝘯𝘨𝘦𝘳 𝘦𝘹𝘪𝘴𝘵𝘴.
𝗜𝗻 𝘀𝘂𝗺𝗺𝗮𝗿𝘆, 𝘄𝗲 𝗰𝗮𝗻𝗻𝗼𝘁 𝘁𝗮𝗸𝗲 𝗲𝗾𝘂𝗶𝘁𝘆-𝗹𝗶𝗸𝗲 𝘁𝗲𝗰𝗵 𝗿𝗶𝘀𝗸 𝘄𝗶𝘁𝗵 𝗰𝗿𝗲𝗱𝗶𝘁-𝗹𝗶𝗸𝗲 𝗿𝗲𝘁𝘂𝗿𝗻𝘀.
As lenders, we look for additional protective factors, including mission-critical use cases, certainty of cash flows eg. through robust offtake arrangements with credible counterparties, and government support.
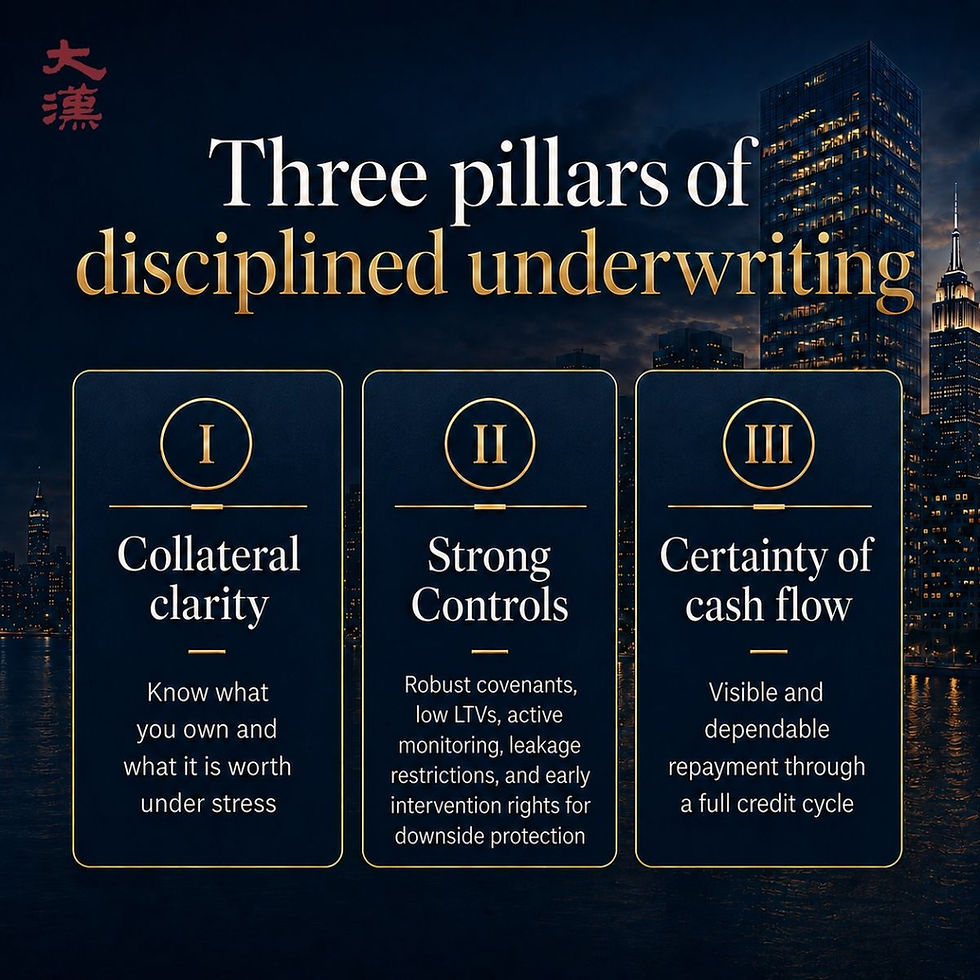
At Tahan Capital, disciplined underwriting means focusing on 𝙨𝙩𝙧𝙤𝙣𝙜 𝙘𝙤𝙣𝙩𝙧𝙤𝙡𝙨, 𝙘𝙤𝙡𝙡𝙖𝙩𝙚𝙧𝙖𝙡 𝙘𝙡𝙖𝙧𝙞𝙩𝙮, and 𝙗𝙪𝙨𝙞𝙣𝙚𝙨𝙨𝙚𝙨 𝙬𝙞𝙩𝙝 𝙨𝙩𝙖𝙗𝙡𝙚 𝙥𝙤𝙨𝙞𝙩𝙞𝙫𝙚 𝙛𝙧𝙚𝙚 𝙘𝙖𝙨𝙝 𝙛𝙡𝙤𝙬 𝙩𝙝𝙖𝙩 𝙘𝙖𝙣 𝙬𝙞𝙩𝙝𝙨𝙩𝙖𝙣𝙙 𝙖 𝙛𝙪𝙡𝙡 𝙘𝙧𝙚𝙙𝙞𝙩 𝙘𝙮𝙘𝙡𝙚.


Comments