top of page

๐—ง๐—ต๐—ฒ ๐—ผ๐—ฝ๐—ฝ๐—ผ๐—ฟ๐˜๐˜‚๐—ป๐—ถ๐˜๐˜† ๐—ถ๐—ป ๐—”๐˜€๐—ถ๐—ฎ ๐—ฝ๐—ฟ๐—ถ๐˜ƒ๐—ฎ๐˜๐—ฒ ๐—ฐ๐—ฟ๐—ฒ๐—ฑ๐—ถ๐˜ ๐—ถ๐˜€ ๐—ป๐—ผ๐˜ ๐—ฎ๐—ฏ๐—ผ๐˜‚๐˜ ๐˜๐—ฎ๐—ธ๐—ถ๐—ป๐—ด ๐—ผ๐—ป ๐—ถ๐—ป๐—ฐ๐—ฟ๐—ฒ๐—บ๐—ฒ๐—ป๐˜๐—ฎ๐—น ๐—ฟ๐—ถ๐˜€๐—ธ ๐˜๐—ผ ๐—ด๐—ฒ๐—ป๐—ฒ๐—ฟ๐—ฎ๐˜๐—ฒ ๐—ฟ๐—ฒ๐˜๐˜‚๐—ฟ๐—ป๐˜€.

Writer: JAZ LOH
JAZ LOH
Apr 23
2 min read

๐—ง๐—ต๐—ฒ ๐—ผ๐—ฝ๐—ฝ๐—ผ๐—ฟ๐˜๐˜‚๐—ป๐—ถ๐˜๐˜† ๐—ถ๐—ป ๐—”๐˜€๐—ถ๐—ฎ ๐—ฝ๐—ฟ๐—ถ๐˜ƒ๐—ฎ๐˜๐—ฒ ๐—ฐ๐—ฟ๐—ฒ๐—ฑ๐—ถ๐˜ ๐—ถ๐˜€ ๐—ป๐—ผ๐˜ ๐—ฎ๐—ฏ๐—ผ๐˜‚๐˜ ๐˜๐—ฎ๐—ธ๐—ถ๐—ป๐—ด ๐—ผ๐—ป ๐—ถ๐—ป๐—ฐ๐—ฟ๐—ฒ๐—บ๐—ฒ๐—ป๐˜๐—ฎ๐—น ๐—ฟ๐—ถ๐˜€๐—ธ ๐˜๐—ผ ๐—ด๐—ฒ๐—ป๐—ฒ๐—ฟ๐—ฎ๐˜๐—ฒ

๐—ฟ๐—ฒ๐˜๐˜‚๐—ฟ๐—ป๐˜€. Rather, it lies in being appropriately compensated for disciplined lending in an underserved market.ย 


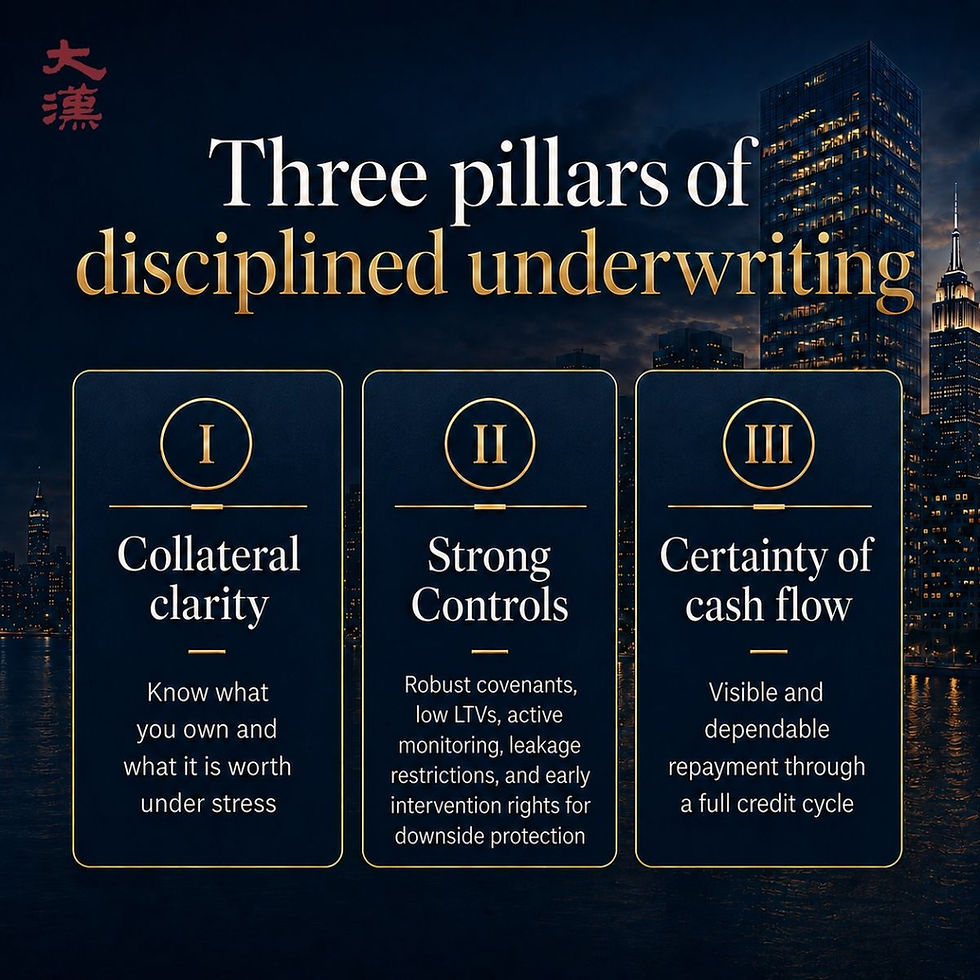
As Howard Marks observed, โ€œIf we avoid the losers, the winners will take care of themselves,โ€, and as Charlie Munger noted, โ€œThe first rule of compounding: never interrupt it unnecessarily.โ€ In this context, ๐—ฑ๐—ถ๐˜€๐—ฐ๐—ถ๐—ฝ๐—น๐—ถ๐—ป๐—ฒ๐—ฑ ๐˜‚๐—ป๐—ฑ๐—ฒ๐—ฟ๐˜„๐—ฟ๐—ถ๐˜๐—ถ๐—ป๐—ด ๐—ฒ๐—ป๐—ฎ๐—ฏ๐—น๐—ฒ๐˜€ ๐—ฟ๐—ฒ๐˜๐˜‚๐—ฟ๐—ป๐˜€ ๐˜๐—ผ ๐—ฎ๐—ฐ๐—ฐ๐—ฟ๐˜‚๐—ฒ ๐˜€๐˜๐—ฒ๐—ฎ๐—ฑ๐—ถ๐—น๐˜† ๐—ผ๐˜ƒ๐—ฒ๐—ฟ ๐˜๐—ถ๐—บ๐—ฒ.


Jamie Dimonโ€™s recent comments in the Financial Times on weakening lending standards and the growing use of payment-in-kind (PIK) structures, where borrowers defer cash payments to lenders, highlight an important ๐˜€๐˜๐—ฟ๐˜‚๐—ฐ๐˜๐˜‚๐—ฟ๐—ฎ๐—น ๐—ฑ๐—ถ๐—ณ๐—ณ๐—ฒ๐—ฟ๐—ฒ๐—ป๐—ฐ๐—ฒ ๐—ฏ๐—ฒ๐˜๐˜„๐—ฒ๐—ฒ๐—ป ๐—จ๐—ฆ ๐—ฎ๐—ป๐—ฑ ๐—”๐˜€๐—ถ๐—ฎ ๐—ฝ๐—ฟ๐—ถ๐˜ƒ๐—ฎ๐˜๐—ฒ ๐—ฐ๐—ฟ๐—ฒ๐—ฑ๐—ถ๐˜.


In the US, a crowded and highly competitive market has compressed spreads. To sustain returns, US lenders are increasingly being pushed down the credit curve - ๐˜ข๐˜ค๐˜ค๐˜ฆ๐˜ฑ๐˜ต๐˜ช๐˜ฏ๐˜จ ๐˜ธ๐˜ฆ๐˜ข๐˜ฌ๐˜ฆ๐˜ณ ๐˜ค๐˜ฐ๐˜ท๐˜ฆ๐˜ฏ๐˜ข๐˜ฏ๐˜ต๐˜ด, ๐˜ฉ๐˜ช๐˜จ๐˜ฉ๐˜ฆ๐˜ณ ๐˜ญ๐˜ฆ๐˜ท๐˜ฆ๐˜ณ๐˜ข๐˜จ๐˜ฆ, ๐˜ข๐˜ฏ๐˜ฅ ๐˜ฎ๐˜ฐ๐˜ณ๐˜ฆ ๐˜ข๐˜จ๐˜จ๐˜ณ๐˜ฆ๐˜ด๐˜ด๐˜ช๐˜ท๐˜ฆ ๐˜ข๐˜ด๐˜ด๐˜ถ๐˜ฎ๐˜ฑ๐˜ต๐˜ช๐˜ฐ๐˜ฏ๐˜ด ๐˜ข๐˜ณ๐˜ฐ๐˜ถ๐˜ฏ๐˜ฅ ๐˜ฃ๐˜ฐ๐˜ณ๐˜ณ๐˜ฐ๐˜ธ๐˜ฆ๐˜ณ ๐˜ค๐˜ข๐˜ด๐˜ฉ ๐˜ง๐˜ญ๐˜ฐ๐˜ธ๐˜ด.


๐—”๐˜€๐—ถ๐—ฎ ๐—ฝ๐—ฟ๐—ฒ๐˜€๐—ฒ๐—ป๐˜๐˜€ ๐—ฎ ๐—ฑ๐—ถ๐—ณ๐—ณ๐—ฒ๐—ฟ๐—ฒ๐—ป๐˜ ๐—ฑ๐˜†๐—ป๐—ฎ๐—บ๐—ถ๐—ฐ.


Despite contributing over a third of global GDP, Asia accounts for only around 7% of global private credit AUM. With SMEs (that make up over 90% of businesses) facing a significant funding gap as banks pull back lending under tighter regulatory constraints, ๐˜๐—ต๐—ฒ ๐—ฑ๐—ฒ๐—บ๐—ฎ๐—ป๐—ฑ ๐—ณ๐—ผ๐—ฟ ๐—ฑ๐—ถ๐—ฟ๐—ฒ๐—ฐ๐˜ ๐—น๐—ฒ๐—ป๐—ฑ๐—ถ๐—ป๐—ด ๐—ถ๐—ป ๐—”๐˜€๐—ถ๐—ฎ ๐—ฟ๐—ฒ๐—บ๐—ฎ๐—ถ๐—ป๐˜€ ๐˜€๐˜๐—ฟ๐—ผ๐—ป๐—ด.


This creates a market where ๐—น๐—ฒ๐—ป๐—ฑ๐—ฒ๐—ฟ๐˜€ ๐—ฐ๐—ฎ๐—ป ๐˜€๐˜๐—ถ๐—น๐—น ๐—ป๐—ฒ๐—ด๐—ผ๐˜๐—ถ๐—ฎ๐˜๐—ฒ ๐—ณ๐—ผ๐—ฟ ๐˜๐—ถ๐—ด๐—ต๐˜๐—ฒ๐—ฟ ๐—ฐ๐—ผ๐˜ƒ๐—ฒ๐—ป๐—ฎ๐—ป๐˜๐˜€, ๐˜€๐˜๐—ฟ๐—ผ๐—ป๐—ด๐—ฒ๐—ฟ ๐—ฐ๐—ผ๐—ป๐˜๐—ฟ๐—ผ๐—น๐˜€, ๐—ฎ๐—ป๐—ฑ ๐—ต๐—ถ๐—ด๐—ต๐—ฒ๐—ฟ-๐—พ๐˜‚๐—ฎ๐—น๐—ถ๐˜๐˜† ๐—ฐ๐—ผ๐—น๐—น๐—ฎ๐˜๐—ฒ๐—ฟ๐—ฎ๐—น ๐—ถ๐—ป ๐—ฏ๐—ฒ๐˜€๐—ฝ๐—ผ๐—ธ๐—ฒ ๐˜€๐˜๐—ฟ๐˜‚๐—ฐ๐˜๐˜‚๐—ฟ๐—ฒ๐˜€ ๐˜๐—ผ ๐—ฝ๐—ฟ๐—ผ๐˜๐—ฒ๐—ฐ๐˜ ๐˜๐—ต๐—ฒ ๐—ฑ๐—ผ๐˜„๐—ป๐˜€๐—ถ๐—ฑ๐—ฒ.


๐˜›๐˜ฉ๐˜ฆ ๐˜ช๐˜ฏ๐˜ง๐˜ฐ๐˜ณ๐˜ฎ๐˜ข๐˜ต๐˜ช๐˜ฐ๐˜ฏ ๐˜ฑ๐˜ณ๐˜ฐ๐˜ท๐˜ช๐˜ฅ๐˜ฆ๐˜ฅ ๐˜ช๐˜ฏ ๐˜ต๐˜ฉ๐˜ช๐˜ด ๐˜ฑ๐˜ฐ๐˜ด๐˜ต ๐˜ช๐˜ด ๐˜ง๐˜ฐ๐˜ณ ๐˜ช๐˜ฏ๐˜ง๐˜ฐ๐˜ณ๐˜ฎ๐˜ข๐˜ต๐˜ช๐˜ฐ๐˜ฏ๐˜ข๐˜ญ ๐˜ฑ๐˜ถ๐˜ณ๐˜ฑ๐˜ฐ๐˜ด๐˜ฆ๐˜ด ๐˜ฐ๐˜ฏ๐˜ญ๐˜บ ๐˜ข๐˜ฏ๐˜ฅ ๐˜ด๐˜ฉ๐˜ฐ๐˜ถ๐˜ญ๐˜ฅ ๐˜ฏ๐˜ฐ๐˜ต ๐˜ฃ๐˜ฆ ๐˜ค๐˜ฐ๐˜ฏ๐˜ด๐˜ต๐˜ณ๐˜ถ๐˜ฆ๐˜ฅ ๐˜ข๐˜ด ๐˜ง๐˜ช๐˜ฏ๐˜ข๐˜ฏ๐˜ค๐˜ช๐˜ข๐˜ญ, ๐˜ช๐˜ฏ๐˜ท๐˜ฆ๐˜ด๐˜ต๐˜ฎ๐˜ฆ๐˜ฏ๐˜ต, ๐˜ฐ๐˜ณ ๐˜ฑ๐˜ณ๐˜ฐ๐˜ง๐˜ฆ๐˜ด๐˜ด๐˜ช๐˜ฐ๐˜ฏ๐˜ข๐˜ญ ๐˜ข๐˜ฅ๐˜ท๐˜ช๐˜ค๐˜ฆ. ๐˜ˆ๐˜ญ๐˜ธ๐˜ข๐˜บ๐˜ด ๐˜ค๐˜ฐ๐˜ฏ๐˜ฅ๐˜ถ๐˜ค๐˜ต ๐˜บ๐˜ฐ๐˜ถ๐˜ณ ๐˜ฐ๐˜ธ๐˜ฏ ๐˜ณ๐˜ฆ๐˜ด๐˜ฆ๐˜ข๐˜ณ๐˜ค๐˜ฉ ๐˜ข๐˜ฏ๐˜ฅ ๐˜ค๐˜ฐ๐˜ฏ๐˜ด๐˜ถ๐˜ญ๐˜ต ๐˜ธ๐˜ช๐˜ต๐˜ฉ ๐˜ข ๐˜ฒ๐˜ถ๐˜ข๐˜ญ๐˜ช๐˜ง๐˜ช๐˜ฆ๐˜ฅ ๐˜ง๐˜ช๐˜ฏ๐˜ข๐˜ฏ๐˜ค๐˜ช๐˜ข๐˜ญ ๐˜ข๐˜ฅ๐˜ท๐˜ช๐˜ด๐˜ฐ๐˜ณ ๐˜ฃ๐˜ฆ๐˜ง๐˜ฐ๐˜ณ๐˜ฆ ๐˜ฎ๐˜ข๐˜ฌ๐˜ช๐˜ฏ๐˜จ ๐˜ข๐˜ฏ๐˜บ ๐˜ช๐˜ฏ๐˜ท๐˜ฆ๐˜ด๐˜ต๐˜ฎ๐˜ฆ๐˜ฏ๐˜ต ๐˜ฅ๐˜ฆ๐˜ค๐˜ช๐˜ด๐˜ช๐˜ฐ๐˜ฏ๐˜ด. ๐˜—๐˜ข๐˜ด๐˜ต ๐˜ฑ๐˜ฆ๐˜ณ๐˜ง๐˜ฐ๐˜ณ๐˜ฎ๐˜ข๐˜ฏ๐˜ค๐˜ฆ ๐˜ช๐˜ด ๐˜ฏ๐˜ฐ๐˜ต ๐˜ช๐˜ฏ๐˜ฅ๐˜ช๐˜ค๐˜ข๐˜ต๐˜ช๐˜ท๐˜ฆ ๐˜ฐ๐˜ง ๐˜ง๐˜ถ๐˜ต๐˜ถ๐˜ณ๐˜ฆ ๐˜ณ๐˜ฆ๐˜ด๐˜ถ๐˜ญ๐˜ต๐˜ด.


Comments


Tahan Capital Management Pte Ltd

ir@tahancapital.com

      (65) 6632 7800

TAHAN ICONS phne n fax-02.png
  • LinkedIn

9 Temasek Boulevard,

Suntec Tower Two #08-02A
Singapore 038989.

Tahan Capital Management Pte. Ltd. holds a Capital Markets Services Licence issued by the Monetary Authority of Singapore for the regulated activity of fund management.
 

The information contained on this website is provided for general information purposes only and does not constitute an offer, invitation, solicitation or recommendation to subscribe for, purchase or sell any investment product or to participate in any investment strategy.

© 2026 Tahan Capital Management Pte. Ltd. All rights reserved.

bottom of page